A family office is a coordinated wealth management system that handles investments, taxes, estate planning, cash flow, giving, and family decision-making for one household or several related households. The family office mindset matters because you can use the same coordination model without hiring a full private staff or being a billionaire.
If your financial life has outgrown scattered accounts, disconnected advisors, and once-a-year planning, this idea is worth understanding. You’ll see what a family office does, how single-family and multi-family offices differ, what the real cost thresholds look like, and how to build a lean version around your own finances.
What Is A Family Office?
A family office is a private organization that manages the financial affairs of one wealthy family or multiple families. It usually coordinates investments, planning, administration, and long-term family wealth decisions under one organized structure.
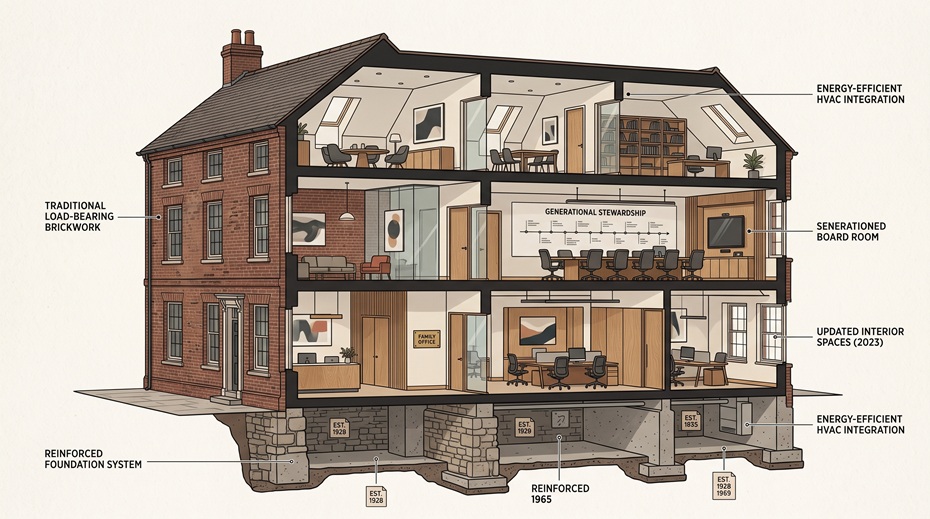
Think of it as the central command center for a family’s financial life. Instead of having an investment advisor, tax professional, estate attorney, insurance advisor, and bookkeeper all working separately, a family office keeps the parts connected. That coordination reduces gaps, duplicated work, and decisions made without seeing the full picture. The aim is not just investment performance; it’s control, continuity, and better decision-making.
A traditional family office may be a dedicated company with employees, outside specialists, reporting systems, and formal governance rules. A leaner version may be a lead advisor coordinating tax planning, estate planning, investment management, and household financial administration. The form matters less than the function. If your advisors communicate, your documents stay current, and your financial choices follow one plan, you’re already thinking like a family office.
What Is The Difference Between A Single Family Office And A Multi-Family Office?
A single family office serves one family, and a multi-family office serves several families through shared staff, systems, and advisory resources. The single-family model offers more control, and the multi-family model spreads cost across multiple households.
A single family office is usually built for families with very large and complex wealth. That may include operating businesses, trusts, real estate, private investments, family philanthropy, multiple homes, and several generations who need coordinated planning. The family pays for dedicated personnel and customized systems. That level of control can be valuable, but the overhead is substantial.
A multi-family office gives you access to family office services without funding the full operation alone. Families with lower asset levels can use shared investment research, planning teams, reporting tools, and administrative support. You give up some customization, but you gain coordination that a standard wealth management relationship may not provide. For many affluent families, that tradeoff is practical.
What Services Does A Family Office Provide?
A family office usually provides investment management, tax coordination, estate planning support, bill payment, family governance, insurance review, reporting, charitable giving support, and cash-flow planning. Many family offices now go beyond portfolio management.
The investment side gets the most attention, but it’s only one part of the job. A family office may help compare public investments, private investments, real estate holdings, business interests, and liquidity needs in one place. It may also track risk across accounts, entities, and family members. That helps you avoid treating each account as if it exists on its own.
The planning and administration side can be just as valuable. Bill pay, document tracking, insurance reviews, estate plan coordination, and charitable giving can prevent small errors from becoming expensive problems. Family governance is another major piece: who makes decisions, how heirs learn about money, how charitable goals are handled, and how family wealth passes across generations. Those conversations can feel uncomfortable, but a family office turns them into scheduled, structured work.
How Much Wealth Do You Need To Start A Family Office?
A traditional single family office is usually discussed at around $100 million in assets, and some experts point to $250 million or more for economic efficiency. A multi-family office may serve families with roughly $5 million to $30 million in investable assets, depending on the provider and service level.
The reason is simple: staff, systems, legal coordination, investment research, and reporting cost money. If a family pays for a chief investment officer, accountants, administrative staff, outside attorneys, risk reviews, and technology, fixed costs can rise quickly. At lower asset levels, those costs may consume too much of the portfolio. That’s why the full single-family model usually fits families with much larger wealth.
That doesn’t mean the concept is irrelevant below those levels. You can apply the family office mindset by coordinating your financial life, even if you don’t create a private company. The goal is to build one plan for investments, taxes, estate documents, cash flow, insurance, and giving. The size of the balance sheet changes the tools, not the need for coordination.
Can A Non-Billionaire Create A Family Office?
Yes, a non-billionaire can create a family office-style system by using outsourced professionals, shared advisory teams, and organized financial processes. You don’t need a private staff to get many of the same benefits.
The rise of the virtual family office has made this model more accessible. Instead of hiring employees, you can use a lead advisor, tax professional, estate planning attorney, insurance specialist, and bookkeeper who coordinate around one plan. Some wealth management firms describe virtual family office models for families with approximately $1 million to $5 million in assets. The service level varies, so you should compare what’s included rather than rely on the label.
A non-billionaire version works best when you define roles clearly. Someone should own the master plan, schedule reviews, collect documents, and make sure each professional understands the bigger picture. If no one is responsible for coordination, the setup can become a loose collection of advisors. The value comes from orchestration, not from calling it a family office.
How Can You Apply The Family Office Mindset Without $100 Million?
You can apply the family office mindset by treating your finances as one connected system. That means your investment choices, taxes, estate plan, insurance, cash reserves, and giving strategy should support the same long-term goals.
Start with a personal financial inventory. List accounts, liabilities, insurance policies, estate documents, tax professionals, advisors, business interests, real estate, and recurring obligations. Then identify where decisions are being made in isolation. A common gap is investment management that ignores tax timing, estate documents that don’t match account titling, or cash reserves that don’t reflect real household spending.
Then build a recurring review rhythm. A quarterly household balance sheet review can cover net worth, cash flow, debt, investment allocation, taxes, and upcoming decisions. An annual planning meeting can include your advisor, tax professional, and estate attorney when needed. The point is to stop reacting to financial events one by one and start managing your wealth as a connected operation.
What Are The 6 Family Office Mindset Principles You Can Use Today?
The six practical principles are coordination, long-term planning, risk control, tax awareness, governance, and administration. These principles work at many wealth levels because they’re based on behavior and organization, not just asset size.
Coordination comes first. Your professionals need to share enough information to avoid conflicting advice. Long-term planning keeps your decisions tied to goals that may span decades, including retirement, business transition, legacy planning, or charitable giving. Risk control means you look beyond market volatility and review debt, insurance, concentration risk, cybersecurity habits, and family dependence on one income source or asset.
Tax awareness means you consider timing, account type, charitable strategy, and ownership structure before making financial moves. Governance means you set decision rules for your household, especially if wealth affects children, aging parents, shared property, or a family business. Administration means bills get paid, documents stay organized, beneficiaries stay updated, and important records are easy to find. These habits sound simple, but they separate organized wealth from scattered wealth.
How Do You Build A DIY Family Office On Any Budget?
You build a do-it-yourself family office by assigning one person or advisor to coordinate the plan, then creating simple systems for documents, reporting, reviews, and decisions. The goal is not to copy a billionaire’s office; it’s to copy the discipline.
Begin with a central financial file. Include your estate documents, insurance policies, tax returns, investment statements, account beneficiaries, loan documents, property records, passwords storage instructions, advisor contacts, and charitable giving records. Keep it secure and update it on a schedule. If your family couldn’t locate key documents during an emergency, the system needs work.
Then set up a planning calendar. Review investments and cash flow quarterly, tax planning before year-end, insurance annually, estate documents after major life changes, and beneficiary designations at least once a year. If you own a business, rental property, or concentrated stock position, add extra review points. A modest but consistent process can do more for you than a complex plan that never gets maintained.
Is A Multi-Family Office Or Outsourced Chief Financial Officer Right For You?
A multi-family office or outsourced chief financial officer may fit if your finances are complex enough that basic investment management no longer covers your needs. Look for coordination, planning depth, transparent fees, and clear accountability.
You may be ready if you have multiple advisors who rarely communicate, a growing tax burden, a business sale on the horizon, real estate holdings, family trusts, charitable plans, or family members who need financial education. You may also need support if your time is being consumed by financial administration. Complexity, not ego, should drive the decision. Paying for coordination only makes sense when coordination solves real problems.
Before hiring, ask direct questions. Who leads the relationship? Which services are performed in-house, and which are outsourced? How are fees charged? How often will your full plan be reviewed? A strong provider should be able to explain the service model without hiding behind polished language.
What Are The Common Misconceptions About Family Offices?
The biggest misconception is that a family office is just an investment firm for billionaires. Another misconception is that the label itself creates better outcomes.
A family office can invest money, but its broader value comes from coordination. If the office only manages a portfolio and ignores taxes, estate planning, family communication, and cash-flow needs, it may not deliver the benefits people expect. The family office name can be used loosely, so you need to examine the actual service menu. Titles matter less than documented responsibilities, reporting, and follow-through.
Another misconception is that tax savings are automatic. A family office can coordinate tax planning, but benefits depend on your assets, income, location, entities, charitable plans, and professional advice. No structure should be adopted just because it sounds elite. The right move is the one that reduces friction, improves decisions, and fits the economics of your situation.
What Is The One Move That Can Elevate Your Financial Strategy?
The fastest move is to create one coordinated annual financial review with every major part of your financial life represented. That review should connect investments, taxes, estate planning, insurance, debt, cash flow, and major life decisions.
This meeting doesn’t need to be formal or expensive. You can begin with a written agenda, your balance sheet, your prior tax return, your estate documents, your insurance summary, and your investment allocation. From there, identify conflicts and missing pieces. Are your beneficiaries current? Does your investment risk match your cash needs? Are your estate documents aligned with account ownership?
That single review gives you the practical benefit of a family office without the full cost. It forces coordination, exposes weak spots, and creates a decision record. Over time, it helps you move from scattered financial tasks to organized wealth management. That’s the family office mindset in action.
What Is A Family Office Mindset?
- Coordinate investments, taxes, estate planning, and cash flow.
- Use shared advisors or outsourced support when needed.
- Treat wealth like a long-term family system.
Think Like A Family Office Before You Pay For One
A family office is not magic, and it’s not only a status symbol. At its best, it gives you coordination, planning discipline, cleaner administration, and better communication across the people who touch your money. You may never need a full single-family office, but you can still use the family office mindset to organize your financial life with more care. Start by centralizing records, assigning coordination, reviewing your full financial picture on a schedule, and choosing advisors who can work together. The result is simple: fewer disconnected decisions and a wealth plan that acts more like a system.
References
- Investopedia — Family Offices Definition
- Forbes — How Much Money Do You Need To Start A Family Office?
- Deloitte Private — The Family Office Market
- Schwab Advisor Services — What To Look For In A Multi-Family Office
- CNBC — Family Offices Are Offering More Than Investment Management
- Kiplinger — Family Office For Everyone
- Forbes — The Family Office Mindset.
Brook Church-Koegel is the founder and CEO of Alpha Capital Management, an asset management firm that invests as a co-GP alongside institutional investors, and the founder of Advisors Edge and the Insurance Education Institute. He lives in Southern California. Read Brook’s biography.